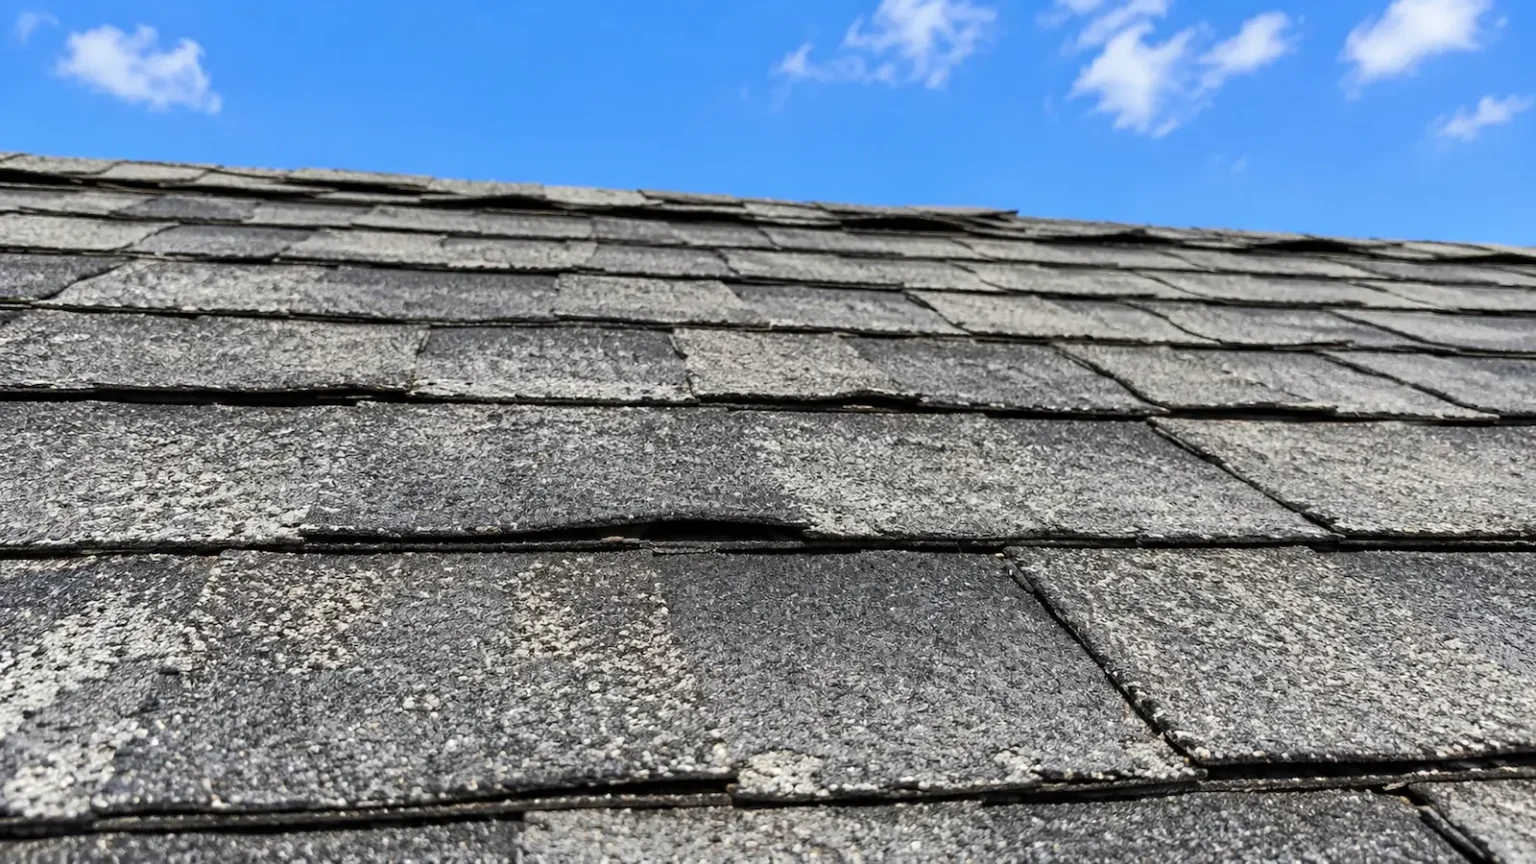
In Houston, the roof is usually the first part of a house to take a beating. Hail, high wind, and tropical storms all hit it hardest. That is also why your roof’s age and the way your policy pays for roof damage can make a bigger difference to a claim check than almost anything else in your home insurance.
This guide explains the difference between actual cash value and replacement cost roof coverage, how roof age can change your coverage at renewal, and what to ask before the next storm.
Key takeaways
- Replacement cost coverage pays to replace a damaged roof at today’s prices, minus your deductible, no matter how old the roof is.
- Actual cash value (ACV) coverage subtracts depreciation for age and wear, so an older roof can pay out much less, sometimes nothing after the deductible.
- Some insurers switch roof coverage from replacement cost to ACV once a roof reaches a certain age, or limit coverage if the roof is in poor condition.
- Check your declarations page and any roof endorsement at every renewal, and tell your insurer when you replace your roof.
Actual cash value vs. replacement cost: the basic difference
The Texas Department of Insurance explains it simply in its home insurance guide:
- Replacement cost pays to repair or replace your home at current prices.
- Actual cash value pays replacement cost minus depreciation, which is the value lost to age and wear.
ACV policies usually cost less, but they also pay less when you have a claim. TDI recommends replacement cost coverage if you want to be fully protected.
How roof age changes what you get paid
TDI uses a roof example to show the difference. Say a storm destroys a roof that costs $10,000 to replace, on a home with a $4,000 deductible (see TDI’s example).
With replacement cost coverage, the age of the roof does not matter:
- Cost to replace the roof: $10,000
- Minus deductible: $4,000
- Policy pays: $6,000
With actual cash value coverage, the payment shrinks as the roof gets older:
- 5-year-old roof: ACV of $8,500, minus $4,000 deductible, policy pays $4,500
- 10-year-old roof: ACV of $7,000, minus $4,000 deductible, policy pays $3,000
- 20-year-old roof: ACV of $4,000, minus $4,000 deductible, policy pays $0
These are TDI’s sample numbers. Your home’s value, deductible, and the insurer’s depreciation method will be different, but the pattern holds: the older the roof, the bigger the gap you cover yourself.
Why your roof coverage can change at renewal
According to TDI’s renewal checklist, when a roof reaches a certain age, an insurance company might switch the policy from replacement cost to actual cash value for the roof. If the roof is in poor condition, the company might drop roof coverage altogether.
Some policies also use a roof payment schedule, which pays a set percentage of the roof’s replacement cost based on its age and material. The percentages vary by company and policy form, so read the endorsement itself rather than assuming.
These changes usually show up in your renewal paperwork. If you skim renewals, this is the one section worth slowing down for.
Your wind and hail deductible matters too
In Houston, roof claims usually come from wind and hail, and many policies carry a separate wind and hail deductible, often a percentage of your dwelling coverage rather than a flat dollar amount. A higher deductible combined with ACV roof coverage can leave very little for the insurer to pay on an older roof.
We break down percentage deductibles and TWIA in our guide to Texas windstorm insurance deductibles.
Questions to ask your agent about your roof
TDI suggests a few questions to ask when you buy or renew a policy (what to know about insurance and your roof). We would add a couple of our own:
- Is my roof’s age and material correct on my policy? An old install date on file can cost you coverage or money.
- How will my policy pay for roof damage? Replacement cost, actual cash value, or a payment schedule?
- Will that change as my roof gets older? Ask whether there is an age when the terms switch.
- What is my wind and hail deductible in dollars? Percentages are easy to underestimate.
- If part of my roof is damaged, will the policy replace the whole roof? Some policies will not pay to replace undamaged sections just because new shingles do not match.
- Can I get a better rate with a new or impact-resistant roof? Many insurers price newer roofs better, and some offer discounts for wind- or hail-resistant materials.
Steps to protect your Houston home
- Find your loss settlement terms. Look at your declarations page and any roof endorsement for the words “actual cash value,” “replacement cost,” or “roof payment schedule.”
- Keep roof records. Save the invoice, permit, and photos from your last roof replacement so you can prove its age and material.
- Tell your insurer after a new roof. TDI recommends updating your company so your policy reflects the new roof’s age, and you may be able to get roof coverage restored or improved.
- Maintain it. Loose or missing shingles and worn flashing can turn a small problem into a denied or reduced claim.
- Compare before renewal. If your company moves your roof to ACV, an independent agent can check whether other carriers still offer replacement cost for your roof’s age and material.
If you ever do need to file, our guide on how to file a home insurance claim in Texas walks through the process. For ways to bring your premium down without giving up roof protection, see lowering home insurance costs in Houston.
Frequently asked questions
Does roof age affect home insurance in Houston?
Yes. Roof age can affect your premium, whether you can get replacement cost coverage on the roof, and how much a policy pays after a covered loss. Some insurers switch older roofs to actual cash value at renewal.
What is actual cash value roof coverage?
It pays the cost to replace your roof minus depreciation for age and wear. On an older roof, the payment can be small, and after a large deductible it may be nothing.
How do I know if my roof has ACV or replacement cost coverage?
Check your declarations page and any roof endorsement, or ask your agent. Look again at every renewal, since roof terms can change as the roof ages.
Get your roof coverage reviewed
Truong Insurance has helped Houston homeowners since 2012. As an independent agency, we can review how your current policy treats your roof and compare options from multiple carriers if your coverage is changing. Our multilingual team is here to help.
Call (281) 377-5049 or contact us to schedule a review. Our office is at 16365 Park Ten Place Dr, Suite 205, Houston, TX 77084, open Monday through Friday from 9 a.m. to 6 p.m.